Build an approval‑ready credit profile
Understand what’s driving your credit decisions, identify items that may be unfair or inaccurate, and take a structured next step toward stronger approvals and better terms.
Built around established U.S. credit reporting practices and dispute procedures under the Fair Credit Reporting Act (FCRA). No unrealistic promises—just clarity, documentation, and structured credit improvement.
Unlock more options
Choose the outcome you care about. We’ll outline what improves it—and what to watch for—so you can move forward with confidence.
Your path to stronger credit
A stronger credit profile can mean better approval odds, improved loan terms, and more financial flexibility. Get a clear, no-fluff overview of what credit improvement can help you achieve — then take the next step when you're ready.
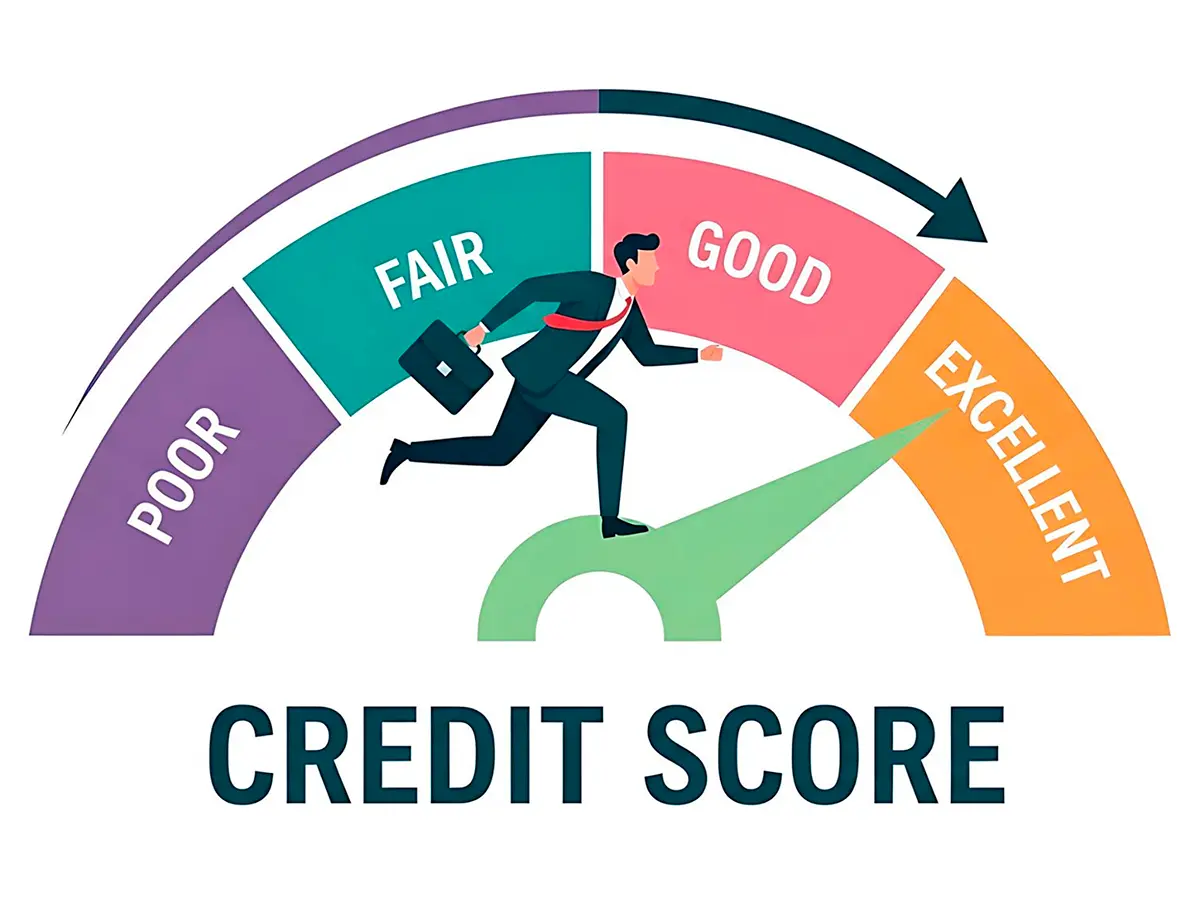
Credit decisions in the U.S. are typically influenced by payment history, utilization ratios, account age, recent inquiries, and the accuracy of reporting across major credit bureaus.
Even small inconsistencies can affect lending algorithms. A structured credit improvement approach focuses on verified data, responsible usage patterns, and consistent financial behavior.
*Results vary. This page does not guarantee outcomes.
How it works
A straightforward workflow used by reputable credit‑support programs: review, challenge what’s questionable, and build stronger habits while updates are processed.
Review your starting point
Clarify your goal and look at what’s currently affecting approvals and terms.
Identify what can be challenged
See what information is typically needed, what to expect next, and how the workflow usually looks.
Move forward
Continue to explore available options and take the next step toward better credit outcomes.
how to clean up credit report without wasting money
I'm skeptical of magic fixes. Still, getting your data accurate and using a few disciplined moves can lower interest, shrink insurance premiums, and cut deposits. That's real cash. Treat this like a tidy-up project, not a makeover. You don't need pricey services - just attention and a calendar. Here's the lean path I actually trust.
Get every report, map the errors
Pull your Equifax, Experian, and TransUnion files (you can get them for free regularly). Scan line by line and build a short list of items to fix.
- Flag duplicates, wrong balances or credit limits, misdated late payments, and accounts that should've aged off (most negatives drop after seven years; many bankruptcies after ten).
- Capture proof: statements, emails, payment confirmations, ID. Screenshots beat memory.
- Prioritize what changes scores fastest: utilization mistakes and any fresh negative marks.
Dispute precisely, not loudly
Submit disputes to each bureau that shows the error. Be specific: "Account 1234 shows a $2,100 balance; statement shows $1,050 as of May 3." Attach evidence. Bureaus usually have around 30 days. Ask for deletion when the item isn't yours or is obsolete; ask for correction when data is wrong. Keep a file: what you sent, where, and when. One corrected limit or balance can drop utilization and nudge scores within a cycle, which can mean a cheaper refinance and hundreds saved over a loan's life.
Collections and late pays
For a one-off late after years of on-time history, try a goodwill request - short, polite, factual. For collections, negotiate before you pay. If a collector agrees to delete, get it in writing first. Note: paid medical collections often vanish from reports and small-dollar medical collections may not report at all; verify current rules and use them.
Validate before you pay collectors
If a collector contacts you, send a debt validation letter quickly. They must show proof the debt is yours and accurate. If they can't, dispute with the bureaus citing the failure to validate. Unsupported items should be removed rather than "updated."
Lower utilization fast
Balances drive scores. Pay cards before the statement date, not just by the due date. Make a mid-cycle micropayment. Ask for a credit limit increase (preferably without a hard pull). Keep old accounts open to preserve available credit. Aim under 30% utilization overall - and under 10% if you want a visible lift that can reduce APR offers.
A quick win I doubted
On a lunch break, I spotted a duplicate medical collection on Experian that wasn't on the other two reports. I filed a short dispute with a screenshot of the zeroed hospital bill. It disappeared the next month; my auto-loan refi quote dropped enough to save me a few hundred over the term. Not a miracle - just paperwork that paid.
Protect the cleanup
- Turn on autopay for minimums to avoid accidental lates.
- Set balance and due-date alerts.
- Freeze credit to block surprise accounts.
- Don't close your oldest card.
- Schedule a 90-day check-in; repeat the small wins.
Mistakes to skip
- Carpet-bomb disputes without evidence.
- Paying a collection before negotiating terms.
- Opening several new accounts at once for "points."
- Ignoring mail from bureaus or lenders.
No magic here - just clear records, steady habits, and timely follow-through. Tackle one item a week; each correction compounds into savings, and the next statement cycle can start showing the difference, with more room to improve.
It's a good idea to seasonally "deep clean" your credit history. Like your home, clean everything in your report that's dirty, broken, and polish what you have.
5 Ways to Clean Up Your Credit - 1. Request copies of your credit reports - 2. Correct inaccuracies in your reports - 4. Improve your FICO score - 5. Beware of ...
A late payment will be removed from your credit reports after seven years. However, late payments generally have less influence on your credit scores as more ...
Frequently asked questions
A clear next step — without the guesswork
See what’s impacting approvals and what may deserve a closer look.
Understand how disputes are structured and what documentation matters.
Improve utilization, consistency, and long-term credit stability.
See what improving your credit could change
Take a structured next step based on your current profile — and decide with clarity.